Tuesday, November 24, 2015

Pradhanmantri Suraksha Beema Yojana - New Insurance Plan by Prime Minister Narendra Modi

People have been very excited about the recently launched social security schemes – Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY),Pradhan Mantri Suraksha Bima Yojana (PMSBY)and Atal Pension Yojana (APY). They are flocking to their banks to get more details about all these schemes and get themselves subscribed to these schemes as early as possible.
With a life cover of Rs. 2 lakhs, I think PMJJBY is a great scheme which promises to cover India’s entire population for a low annual premium of just Rs. 330. This scheme is highly suitable to our working population on whom their family members are dependent for their survival and growth. On the other hand, at an annual premium of Rs. 12 for an accidental disability and death cover of upto Rs. 2 lakhs, there is no doubt in my mind that PMSBY is a really cheap mode of getting yourself covered against fatal accidents.
But, if I analyze whether PMJJBY is the cheapest term plan available in the market with an annual premium of Rs. 330 for a life cover of Rs. 2 lakhs, I find that it is not the case if you are a relatively young person, can afford to pay higher premiums and probably don’t mind getting yourself covered with private insurers as well. In other words, there are some better options available in the market as compared to PMJJBY with proportionately lower premiums and higher sum assured.
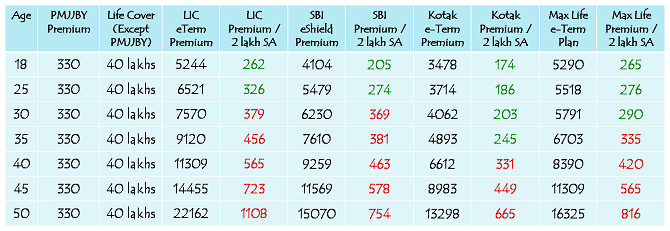
PMJJBY vs. LIC eTerm, SBI eShield, Kotak Preferred e-Term & Max Online Term Plan
Picture 5
Note: All figures in the table above are in Rupees, except Age.
LIC is the most trusted life insurance company in India with the highest claim settlement ratio. It is a known fact and I need not convince anybody about this fact. If you check the table above, LIC’s online term plan – LIC eTerm Plan, is costing Rs. 5,244 and Rs. 6,521 for a cover of Rs. 40 lakhs to a couple of individuals, aged 18 years and 25 years respectively. If I divide Rs. 40 lakhs by 20, I get a cover of Rs. 2 lakhs and if divide Rs. 5,244 and Rs. 6,521 by 20, then I get Rs. 262 and Rs. 326 respectively.
Rs. 262 and Rs. 326 are the premiums I need to pay to LIC per Rs. 2 lakhs of life cover at the age of 18 years and 25 years respectively. I need not emphasize that Rs. 262 and Rs. 326 are lower than Rs. 330 which I would be required to pay as the premium for a life cover of Rs. 2 lakhs when I subscribe to Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY).
As I become older, say more than 25 years of age, LIC starts charging me more for the same life cover of Rs. 40 lakhs. If I am 30 years old, LIC charges me Rs. 379 for a cover of Rs. 2 lakhs and if I am 50 years old, the premium goes up very sharply to Rs. 1,108 for the same life cover. Please note that these are only proportionate premiums and LIC would charge me more if it is to provide only Rs. 2 lakh of life cover.
Similar is the case with SBI Life’s online term plan, SBI eShield. SBI Life charges even less than what LIC charges for its online term plan. For a cover of Rs. 40 lakhs, you need to pay just Rs. 4,104 and Rs. 5,479 if you are 18 and 25 years old respectively. That is Rs. 205 and Rs. 274 respectively for a proportionate life cover of Rs. 2 lakhs.
As you can check from the table above, Kotak Life Insurance provides the cheapest online term insurance among the four companies I decided to select for this comparison. Even Max Life Insurance provides cheaper life cover as compared to LIC, but it is costlier than Kotak Life for all age groups and costlier than SBI Life in some extreme age groups and cheaper in some middle age groups.
So, why PMJJBY is costlier than other Online Term Plans? The answer lies in the fact that every insurance policy has some operational expenses and incentives for the intermediaries which provide services to their customers. All these expenses would be relatively higher for an insurance policy with a lower sum assured and lower premium and relatively lower for an insurance policy with a higher sum assured and higher premium. I think this is the reason why PMJJBY is costlier than other online term plans in some of the age groups.
So, younger age group subscribers would be subsidising older age groups in PMJJBY?Probably yes and rightly so. As you know, in PMJJBY, the premium would remain the same at Rs. 330 for a life cover of Rs. 2 lakhs for all the subscribers aged between 18 and 50 years, and going upto 55 years. We all know that the probability of dying at the age of 50 years or 55 years is way higher than the probability of dying at the age of 18 years or 25 years.
So, ideally the premium for your life cover should be lower at a younger age and higher at an older age, which is there in all other online term plans. But, that is not the case with PMJJBY. In order to keep it fairly simple and beneficial to all the Citizens of India, the government has decided to keep the premium uniform at Rs. 330. Though I do not favour any kind of subsidy and I think either younger subscribers or the government would be subsiding older subscribers in PMJJBY, I think it is a great move to keep it fairly simple and encourage a large population to get associated with PMJJBY.
Service Tax Exemption Advantage – Lastly, I would like to highlight it here that PMJJBY has been exempt from service tax of 14% and that already places this scheme at a slightly advantageous position as against other insurance plans. All other schemes attract service tax and it is included in all the premiums mentioned above in the table.
So, the conclusion of this exercise is that PMJJBY is a great scheme launched by the Modi Government, but if you are a relatively younger subscriber and feel Rs. 2 lakhs of life cover is on a slightly lower side than your actual requirement, then you should opt for an online term plan of a higher value either with LIC or SBI or Kotak Life or even Max Life. Older and eligible subscribers should simply subscribe to PMJJBY as Rs. 330 is the cheapest premium of all for their age groups.
Moreover, I think Pradhan Mantri Suraksha Bima Yojana (PMSBY) is the cheapest accidental death and disability insurance policy and you should definitely subscribe to it. PMSBY covers you till the age of 70 years, as against 50-55 years till which PMJJBY provides you the life cover.

This post is written by Shiv Kukreja, who is a Certified Financial Planner and runs a financial planning firm, Ojas Capital in Delhi/NCR. He can be reached at skukreja@investitude.co.in

Welcome to New LIC Portal

Dear Readers,
       Thanks for Visiting LICPORTAL, I believe insurance is always a personal choice however 

Tuesday, July 15, 2014

Jeevan Mangal - Micro Insurance Plan

LIC’s Micro Insurance Plans are not plans but opportunities that knock on your door once in a lifetime. These plans are a perfect blend of insurance, investment and a lifetime of happiness!.

Introduction:

LIC’s New Jeevan Mangal is a protection plan with return of premiums on maturity, where you may pay the premiums either in lump sum or regularly over the term of the policy. This plan has an in-built Accident Benefit which provides for double risk cover in case of accidental death.


Benefits
  1. Maturity Benefit:
Provided the policy is inforce, on surviving to the date of maturity, “Sum Assured on Maturity” shall be payable which is equal to the total amount of premiums paid during the term of the contract (excluding the taxes and extra premium, if any)
  1. Death Benefit:
Provided the policy is inforce, the death benefit shall be payable as under:-
Death due to any reason other than accident:
For regular premium policies : “Sum Assured on Death” shall be payable which is defined as highest of 10 times of annualised premium or 105% of all the premiums paid as on date of death or Sum assured on Maturity or absolute amount assured to be paid on death where absolute amount assured to be paid on death is Sum Assured.
The premiums mentioned above exclude taxes and extra premium, if any.
For single premium policies : “Sum Assured on Death” shall be payable which is defined as higher of 125% of single premium (excluding the taxes and extra premium, if any) or absolute amount assured to be paid on death where absolute amount assured to be paid on death is Sum Assured.

Death due to accident :
An additional sum equal to Sum Assured shall also be payable.
An ‘Accident’ for the purpose of this policy is defined as “An Accident is a sudden, unforeseen andinvoluntary event caused by external, violent and visible means.

1. Eligibility Conditions and Other Restrictions:
a) Minimum age at entry : 18 years (completed)
b) Maximum age at entry : 55 years (nearest birthday)
c) Maximum age at maturity : 65 years (nearest birthday)
d) Policy Term : 10 to 15 years for regular premium.
5 to 10 years for single premium.
e) Minimum Instalment Premium : Rs 60/- under Monthly Mode
For other modes, there is no specific minimum instalment premium.
f) Minimum Sum Assured : Rs. 10,000/-
g) Maximum Sum Assured : Rs. 50,000/-
(Sum Assured shall be in multiples of Rs. 1,000/-)

2. Payment of Premiums :
The modes of premium payment allowable are Yearly, Half Yearly, Quarterly or Monthly. Single Premium mode is available for terms from 5 to 10 years.
A grace period of two calendar months but not less than 60 days will be allowed for all modes of payments.

3. Sample Premium Rates:
Following are some of the sample premium rates per Rs. 1000/- Sum Assured:
Annual Premium (in Rs.) for Rs.1000 Sum Assured:
Age
(yrs.)
Term of the Policy (years)
10
15
20
58.85
36.85
30
60.15
38.15
40
66.45
43.60
50
83.60
56.15


Single Premium (in Rs.) for Rs.1000 Sum Assured
Age
(yrs.)
Term of the Policy (years)
5
10
20
175.30
138.65
30
179.25
144.40
40
199.85
172.00
50
269.45
247.40


4. Paid-up Value:
In case of regular premium policies, if after at least three full years’ premiums have been paid in respect of this policy and any subsequent premium be not duly paid, this policy shall not be wholly void, but shall subsist as a paid-up policy. The Sum Assured on Death shall be reduced to a sum, called the Death Paid-up Sum Assured. The Death Paid-Up Sum Assured shall bear the same ratio to the Sum Assured on Death as the premiums paid bears to the total number of premiums payable.
On the Life Assured’s death prior to maturity, the Death Paid-Up Sum Assured shall be payable. On Maturity, total premiums paid less taxes and extra premium, if any, shall be payable.

5. Revival:
Subject to production of satisfactory evidence of continued insurability, a lapsed policy can be revived by paying arrears of premium together with interest within a period of two years from the date of first unpaid premium but before maturity. The rate of interest applicable will be as fixed by the Corporation from time to time.

6. Surrender Value:
The Guaranteed Surrender Value available under this plan is as under:
Single Premium policies : The policy may be surrendered for cash at any time during the policy term. The Guaranteed Surrender Value shall be as under:
- Within three policy years from Date of Commencement of policy: 70% of the Single premium excluding taxes and extra premium, if any.
- Thereafter: 90% of the Single premium excluding taxes and extra premium, if any.
Regular Premium policies : The policy may be surrendered for cash provided the premiums have been paid for atleast three consecutive years. The Guaranteed Surrender Value shall be equal to Guaranteed Surrender Value factor multiplied by total premiums paid (excluding taxes and extras, if any). The Guaranteed Surrender Value factor will depend on the policy term and policy year in which the policy is surrendered and is as under:
Policy Year
Policy Term
10
11
12
13
14
15
1
0.00%
0.00%
0.00%
0.00%
0.00%
0.00%
2
0.00%
0.00%
0.00%
0.00%
0.00%
0.00%
3
30.00%
30.00%
30.00%
30.00%
30.00%
30.00%
4
50.00%
50.00%
50.00%
50.00%
50.00%
50.00%
5
50.00%
50.00%
50.00%
50.00%
50.00%
50.00%
6
50.00%
50.00%
50.00%
50.00%
50.00%
50.00%
7
50.00%
50.00%
50.00%
50.00%
50.00%
50.00%
8
65.00%
60.00%
57.50%
56.00%
55.00%
54.29%
9
80.00%
70.00%
65.00%
62.00%
60.00%
58.57%
10
80.00%
80.00%
72.50%
68.00%
65.00%
62.86%
11
80.00%
80.00%
74.00%
70.00%
67.14%
12
80.00%
80.00%
75.00%
71.43%
13
80.00%
80.00%
75.71%
14
80.00%
80.00%
15
80.00%
Corporation may, however, pay special surrender value if it is more favourable to the policyholders.

7. Loan:
No loan facility will be available under this plan.

8. Taxes:
Taxes including Service Tax, if any, shall be as per the Tax laws and the rate of tax shall be as applicable from time to time.
The amount of tax as per the prevailing rates shall be payable by the policyholder on the premiums including extra premiums, if any. The amount of Tax paid shall not be considered for the calculation of benefits payable under the plan.

9. Cooling-off period:
If the policyholder is not satisfied with the “Terms and Conditions” of the policy, the policy may be returned to the Corporation within 15 days from the date of receipt of the policy stating the reason of objections. On receipt of the same the Corporation shall cancel the policy and return the amount of premium deposited after deducting the proportionate risk premium for the period on cover and charges for stamp duty.

10. Exclusions:
a) Suicide :
Under Single Premium policies :
The policy shall be void if the Life Assured (whether sane or insane) commits suicide at any time within 12 months from the date of commencement of risk and the Corporation will not entertain any claim under this policy except to the extent of 90% of the single premium paid excluding taxes and any extra premium paid.
Under Regular Premium policies :
This policy shall be void
i. If the Life Assured (whether sane or insane) commits suicide at any time within 12 months from the date of commencement of risk and the Corporation will not entertain any claim under this policy except to the extent of 80% of the premiums paid excluding any taxes and extra premiums, if any, provided the policy is In-force.
ii. If the Life Assured (whether sane or insane) commits suicide within 12 months from date of revival, an amount which is higher of 80% of the premiums paid till the date of death (excluding any taxes and extra premiums, if any) or the surrender value, provided the policy is inforce, shall be payable. The Corporation will not entertain any other claim under this policy.

b) Accident Benefit:
The Corporation will not be liable to pay the additional sum referred if the death of the Life Assured shall:
(i) be caused by intentional self injury, attempted suicide, insanity or immorality or whilst the Life Assured is under the influence or consumption of intoxicating liquor, drug or narcotic; or
(ii) be caused by injuries resulting from taking any part in riots, civil commotion, rebellion, war (whether war be declared or not), invasion, hunting, mountaineering, steeple chasing, racing of any kind, paragliding or parachuting, taking part in adventurous sports; or
(iii) result from the Life Assured committing any breach of law with criminal intent; or

(iv) occur after 180 days from the date of accident of the Life Assured.

                                                        Refer LIC Official Document

For More Info Contact – US or

Call or SMS “Plan” to 9977143290


LIC's e-Term Plan


Key Features :
1.    Available through Online mode (www.licindia.in)
2.    Pure Term plan
3.    Differential premium rates for Smoker/Non-Smoker lives
4.    Proposal on own life ONLY will be considered
o    Death Benefit –    Sum Assured payable on death
o    Maturity Benefit – Not available

Eligibility conditions 
     Minimum Sum Assured             : Rs.25,00,000
                                                    for Smoker                                                    
                                                 :Rs.50,00,000
                                                      for Non-smoker                                                  
Maximum Sum Assured       :   No limit
Minimum age at entry          :  18 years (completed)
Maximum age at entry         :  60 years (nearest birthday)
Maximum cover                    :  75 years (nearest birthday)
Minimum policy term            :  10 years
Maximum policy term           :  35 years
Mode of payment                  :  Yearly
  

Benefits
·         LIC’s e-Term is a regular premium non-participating “on-line term assurance policy” which provides financial protection to the insured’s family in case of his/her unfortunate demise. This plan will be available through on-line application process only and no intermediaries will be involved. To purchase this plan please log on to our website www.licindia.in.
·         Under this plan, there are two categories of premium rates namely (1) Aggregate lives & (2) Non-smoker lives. For Sum Assured upto Rs. 49 lacs Aggregate category rates only would apply. For Sum Assured Rs. 50 lacs and above there is an option to choose differential premium rate for Non-smoker category. However, the application of Non-smoker rates shall be based on the findings of the Urinary Cotinine test. In all other cases the Aggregate premium rates shall be applicable.
·         Death Benefit: In case of unfortunate death of the Life Assured during the policy term Sum Assured shall be payable.
·         Maturity Benefit: On survival to the end of the policy term, nothing shall be payable.

LIC e-term

Eligibility Conditions and Other Restriction:

  • Minimum Sum Assured          :   Rs. 25,00,000 for Aggregate category
    Rs. 50,00,000 for Non-smoker category
  • Maximum Sum Assured         :   No limit
            (The Sum Assured shall be in multiples of Rs. 1, 00,000/-)
  • Minimum age at entry             :  18 years (completed)
  • Maximum age at entry            :  60 years (nearest birthday)
  • Maximum cover ceasing age             :  75 years (nearest birthday)
  • Minimum policy term              :  10 years
  • Maximum policy term            :  35 years
  • Proposal on own life only will be considered. Key Man Insurance (KMI)/Partnership/EE Cover will not be allowed.

Payment of Premiums:

Premium need to be paid annually during the policy term.
A grace period of one month but not less than 30 days from due date of premium will be allowed for payment of premiums.

Sample Premium Rates: 

The sample premium rates (exclusive of taxes) are as under:
For Aggregate category

Annualised premium rates per Rs. 1000 Sum Assured
 Age
(yrs.)
Term of the Policy (years)
10 15 20 25 30
20 0.92 0.92 0.93 1.00 1.11
30 1.10 1.20 1.39 1.66 1.97
40 2.02 2.48 3.00 3.56 4.19
50 4.86 5.72 6.73 7.90 -
For Non-smoker category

Annualised premium rates per Rs. 1000 Sum Assured
 Age
(yrs.)
Term of the Policy (years)
10 15 20 25 30
20 0.63 0.63 0.65 0.70 0.79
30 0.77 0.85 1.00 1.21 1.46
40 1.48 1.84 2.25 2.69 3.18
50 3.67 4.34 5.13 6.06 -

Revival:

If premiums are not paid within the grace period then the policy will lapse. A lapsed policy can be revived within a period of 2 consecutive years from the date of first unpaid premium but before the expiry of policy term, by paying all the arrears of premium together with interest (compounding half-yearly) at such rate as may be prevailing at the time of the payment, subject to submission of satisfactory evidence of continued insurability.
The cost of the medical reports, including special reports, if any, required for the purposes of revival of the policy, shall be borne by the Life Assured.
The Corporation reserves the right to accept at original terms, accept at revised terms or decline the revival of a discontinued policy. The revival of discontinued policy shall take effect only after the same is approved by the Corporation and is specifically communicated to the Policyholder.

Paid-up Value:

The policy shall not acquire any paid-up value.

Surrender Value:

No Surrender Value will be available under this plan.

Taxes: 

Taxes including Service Tax, if any, shall be as per the Tax laws and the rate of tax shall be as applicable from time to time.
The amount of tax as per the prevailing rates shall be payable by the Policyholder on Instalment premiums including extra premiums, if any.

Cooling-off period:

If the Policyholder is not satisfied with the “Terms and Conditions” of the policy, the policy may be returned to us within 30 days from the date of receipt of the policy bond stating the reason of objections. On receipt of the same the Corporation shall cancel the policy and return the amount of premium deposited after deducting the proportionate risk premium for the period on cover, stamp duty charges, expenses for medical examination and special reports, if any.

Exclusion:                                         "Have Doubt ?"  Contact Us

Suicide: 
This policy shall be void if the Life Assured (whether sane or insane) commits suicide at any time within 12 months from the date of commencement of risk or within 12 months from the date of revival and the Corporation will not entertain any claim under this policy except to the extent of 80% of the premiums paid till the date of death excluding any taxes, extra premium, if any, provided the policy is inforce.

How to purchase LIC’s e-Term

Step-by-step process to buy LIC’s e-TERM Online:
  • Log-on to our website (www.licindia.in) for buying this online product. Click on ‘Buy Online’.  Select e-Term.
  • Choose your desired Sum Assured and the Policy Term (the period for which you want the cover). The Sum Assured will be paid to the nominee on the unfortunate event of the death of the policy-holder.
  • Enter Basic details - Name, Age, Gender, Qualification, etc in the form displayed on your screen.
  • After filling in the details, a premium calculator will calculate the premium for the chosen parameters. The Premium will depend on the age, gender, term, sum-assured, health and tobacco-usage. Lower premium rates are applied to non-tobacco users for Sum Assured more than 50 Lakhs.
  • Premium payment mode – Annual.
  • Complete the form online with these details and pay premium online – at www.licindia.in.
                                                   "Have Doubt ?"  Contact Us
Section 45 of Insurance Act, 1938:
No policy of life insurance shall after the expiry of two years from the date on which it was effected, be called in question by an insurer on the ground that a statement made in the proposal for insurance or in any report of a medical officer, or referee, or friend of the insured, or in any other document leading to the issue of the policy, was inaccurate or false, unless the insurer shows that such statement was on a material matter or suppressed facts which it was material to disclose and that it was fraudulently made by the policyholder and that the policyholder knew at the time of making it that the statement was false or that it suppressed facts which it was material to disclose.
Provided that nothing in this section shall prevent the insurer from calling for proof of age at any time if he is entitled to do so, and no policy shall be deemed to be called in question merely because the terms of the policy are adjusted on subsequent proof that the age of the life assured was incorrectly stated in the proposal.
                                                "Have Doubt ?"  Contact Us
Prohibition of Rebates (Section 41 of INSURANCE ACT, 1938) :
(1) No person shall allow or offer to allow, either directly or indirectly, as an inducement to any person to take out or renew or continue an insurance in respect of any kind of risk relating to lives or property in India, any rebate of the whole or part of the commission payable or any rebate of the premium shown on the policy nor shall any person taking out or renewing or continuing a policy accept any rebate except such rebates as may be allowed in accordance with the published prospectuses or tables of the insurer provided that acceptance by an insurance agent of commission in connection with a policy of life insurance taking out by himself on his own life shall not be deemed to be acceptance of a rebate of premium within the meaning of this sub-section if at the time of such acceptance the insurance agent satisfies the prescribed conditions establishing that he is a bona fide insurance agent employed by the insurer.

(2) Any person making default in complying with the provision of this Section shall be punishable with a fine, which may extend to 500 rupees